Health and wellness has the best repurchase economics in DTC eCommerce, and it’s also the category most likely to fool operators into thinking retention is working when it isn’t. Supplements post a 37.7% repurchase rate within 24 months, better than beauty, fashion, or nearly anything else consumers buy online, according to 24-month supplement repurchase benchmark data. That number looks like validation. It usually isn’t. It’s a lagging average that hides the one moment where most health and wellness brands actually lose the customer: the first reorder.
Recharge’s 2026 subscription data, drawn from more than 20,000 brands, shows supplements converting only 86.6% of customers into a second order, the leakiest first-reorder rate of any wellness vertical they track, per Recharge’s subscription retention research. Compare that to coffee and tea at 99.3% or beauty at 97.5%. The category with the strongest long-term repurchase ceiling has one of the weakest openings. That gap between “great category economics” and “leaky first reorder” is the entire 2026 retention story for health and wellness brands, and it’s why acquisition-first thinking keeps producing flat cohorts even when top-line revenue looks fine.
This article works through the benchmarks that matter for supplement, skincare, and wellness subscription brands running at meaningful volume, why several published numbers disagree by a factor of two or three, and where to put your retention effort so it actually moves the reorder curve instead of just the vanity metric.
What you’ll find in this benchmark breakdown
- Why repeat purchase rate benchmarks vary so widely across sources, and how to read your own number correctly
- The 2026 health and wellness benchmark stack: repeat rate by vertical, email revenue share, and category-specific open and click rates
- Where the retention curve actually breaks, using order-sequence data from subscription platforms
- How flows and campaigns split revenue in a replenishment category, and which flow types carry the weight
- The wellness-specific traps that don’t show up in generic eCommerce retention advice
- A practical framework for calibrating your numbers to your own depletion cycle instead of a cross-vertical median
Benchmarks that mean nothing without a measurement window
Before touching a single number, get the definitional issue out of the way, because it’s the difference between an accurate diagnosis and a wrong one.
Shopify’s cross-vertical panel puts average repeat customer rate at 28.2% across online retailers, a figure widely cited as the general eCommerce baseline, per a 2026 cross-vertical analysis. That number is useful as a floor, and it’s close to nothing else once you segment by category or time window. A supplement brand on a 30-day reorder cycle and a furniture brand selling once every five years should never be judged against the same repeat rate, and blending them into one average is how brands convince themselves they’re either fine or failing for the wrong reasons.
Here’s where it gets genuinely confusing if you don’t check definitions. One synthesis of Bluecore and Shopify data puts the 12-month repeat purchase rate for health and supplements at roughly 29%, with beauty at 21-26%, fashion at 20-26%, and grocery over 40%, according to Everboost’s repeat purchase rate analysis. A separate source, RetentionLab, puts the 12-month customer-based repeat rate for supplements and wellness brands between $1M and $50M at 38-52%, with top-quartile performers hitting 64%, and skincare and beauty at 28-36%, based on RetentionLab’s benchmark synthesis.
Those two numbers are not the same measurement. Everboost’s figure comes from a broad, all-customer panel across store sizes. RetentionLab’s comes from a narrower band of established, revenue-qualified brands. Averaging them tells you nothing. What you should take from the conflict is this: repeat purchase rate only means something once you fix the window (90-day vs. 12-month) and the cohort (all customers who ever bought vs. brands above a revenue threshold). If you’re benchmarking your own supplement brand, the RetentionLab range is the closer comparison if you’re doing real volume; the Everboost figure is closer to the market-wide average including brands that never built a real retention program.
For a shorter, operational window, the same Everboost data puts a 90-day “good” repeat rate for DTC health and wellness at 15-25%: under 12% is weak for supplements and consumables, 15-22% is typical, and 25%+ is strong. Skincare and haircare brands should expect a similar strong threshold, around 20%+ in the same window. Use the 90-day number for pulling levers quickly and the 12-month number for judging whether your subscription program is structurally healthy.
The health and wellness benchmark stack for 2026
With the definitional issue out of the way, here’s what the category actually looks like this year.
Repeat purchase rate by vertical (12-month). Health and supplements sit around 29% on the broad-panel measure, ahead of beauty (21-26%) and fashion (20-26%), behind grocery (40%+), and well ahead of luxury (roughly 10%), against an all-eCommerce average of 25-30%. The internal takeaway worth sitting with: a repeat rate below 35% in supplements should draw real scrutiny, because the category’s physics support materially higher numbers than most non-consumable verticals will ever see.
Email’s share of total revenue. Klaviyo’s 2026 benchmark data puts email at roughly 27% of total store revenue across its full customer base, but high-repeat consumables including supplements, beauty, food, and pet can sustain 30-45%, per 2026 email revenue share benchmarks. If your email program is contributing less than a quarter of revenue in a consumable category, that’s not a channel problem in isolation, it’s usually a signal that flows aren’t structured around the reorder cycle.
Category-specific email performance. Health and personal-care campaigns run a 30.5% open rate and a 1.24% click rate, both below Klaviyo’s blended all-industry campaign average of 1.69% click, according to a secondary aggregation of Klaviyo benchmark data. Flow performance in the same category holds up much better, around 50% open and 4.62% click. That gap between decent open rates and weak campaign clicks is a recurring pattern in wellness: subscribers open because they trust the sender, but campaigns built around generic promotions don’t earn the click the way behavior-triggered flows do.
For direct comparison, Klaviyo’s broader 2025 benchmark report puts average campaign performance at 37.93% open, 1.29% click, 0.08% placed order rate, and $0.10 revenue per recipient, against automated flows at 48.57% open, 4.67% click, and 1.42% placed order rate, per Klaviyo’s 2025 AMER benchmark report. Health and wellness campaigns underperform even that campaign baseline on clicks, which is the single clearest argument for shifting weight toward flows in this category rather than trying to out-send the problem with more promotional volume.
Where the retention curve actually breaks
This is the section that should change how you allocate resources, because most health and wellness brands are optimizing the wrong point in the customer journey.
Recharge’s order-sequence data tells the real story. Supplements convert 86.6% of first-time subscribers into a second order. From there the curve doesn’t fall off a cliff again, it flattens: 57.6% make it to order three, 33.8% to order four, 9.8% to order seven, and 1.4% are still active at order thirteen, based on Recharge’s supplement subscription research. Health and wellness broadly does slightly better on the opening reorder, at 92.9%, and beauty sits at 97.5%. Pet lands at 96.2%. Supplements are the outlier, and not in a good way.
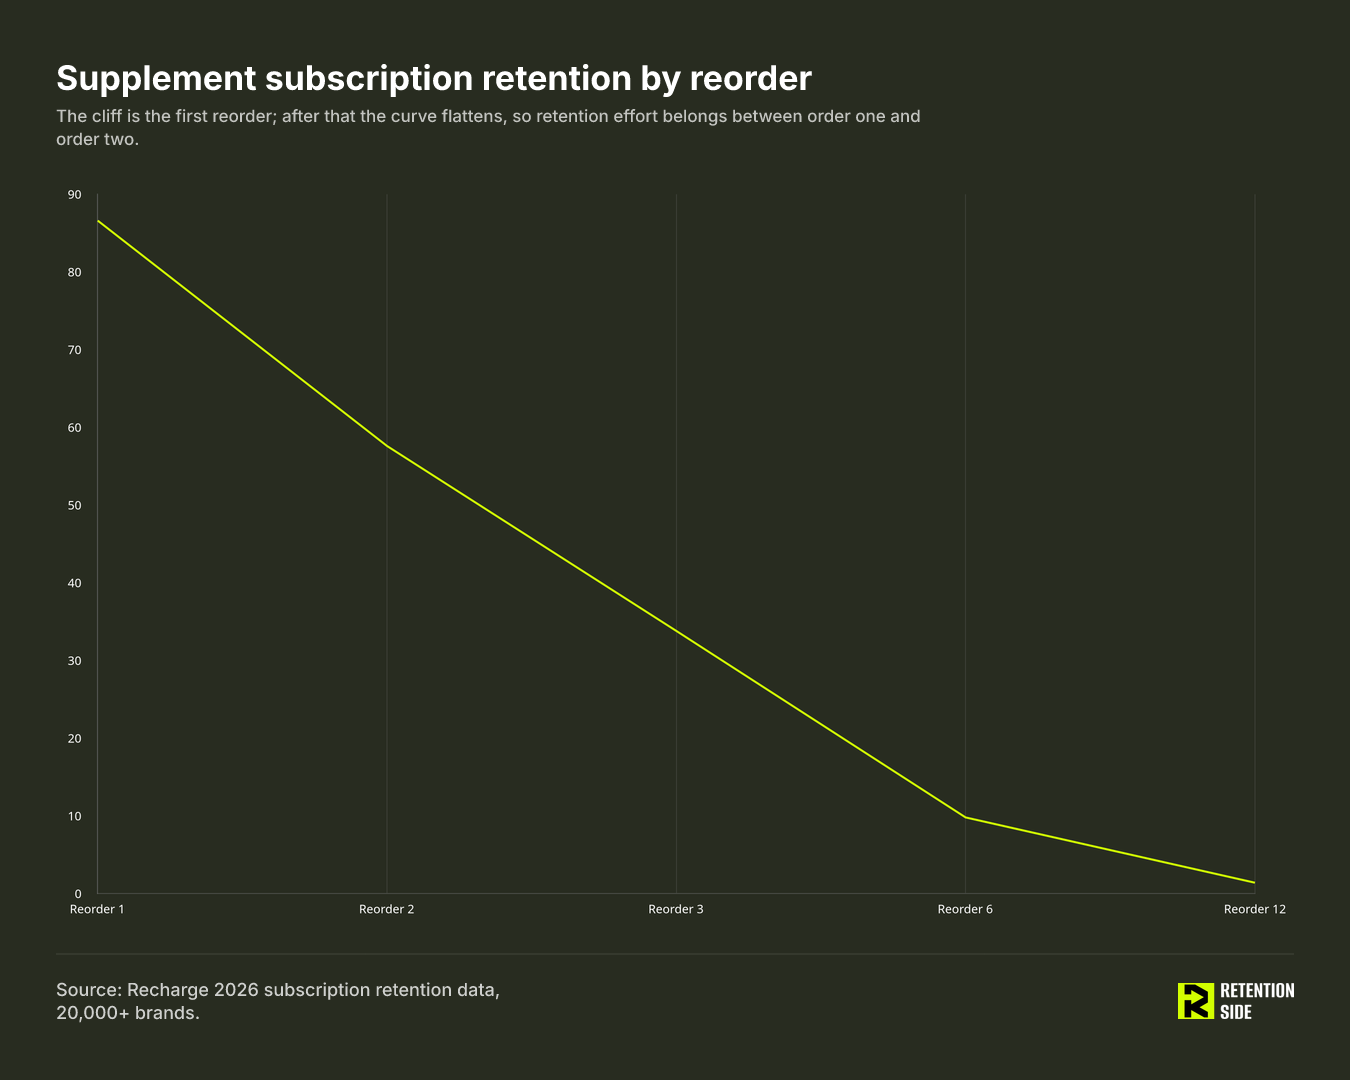
This pattern lines up with Recharge’s separate churn timing data: roughly 61% of voluntary subscription cancellations happen at the first two renewals, and about 72% happen within the first four, according to Recharge’s churn timing analysis. Health and wellness’s first-renewal churn sits at 26.5%, close to food (28.2%) and beauty (26.3%), and far above fashion’s 16.1%.
Put those two data sets together and the operational conclusion is unavoidable: if you’re spending retention budget on win-back flows for customers who churned at order eight, you’re solving a problem that barely exists. The real leverage point sits between order one and order two, before the habit is formed and before the customer has decided whether the product is worth reordering at full price without a first-purchase discount propping up the decision. Lifecycle content, dosage or usage reminders, and proactive reorder nudges belong in that window, not scattered evenly across a generic 90-day flow calendar.
Flows vs. campaigns in a replenishment category
Klaviyo’s 2026 data, drawn from more than 183,000 customers, shows flows generating around 41% of total email revenue from just 5.3% of total sends, with revenue per recipient roughly 18 times higher than campaigns, per Klaviyo’s 2026 email benchmarks. Flow click rate sits at 5.58% against campaigns at 1.69%. Top-performing flows reach $7.59 to $7.79 in revenue per recipient with click rates above 10%. Flows also skew younger in the customer lifecycle, with roughly 48% of flow revenue coming from new buyers, compared to 16% for campaigns.
Breaking flows down by type using Klaviyo’s 2025 benchmark report clarifies where the money actually sits: abandoned cart flows generate $3.07 in revenue per recipient, welcome flows $2.35, browse abandonment $0.95, and post-purchase flows a comparatively modest $0.38. Post-purchase flows carry the highest open rate of any flow type at 59.77%, but the lowest placed order rate at 0.48%.
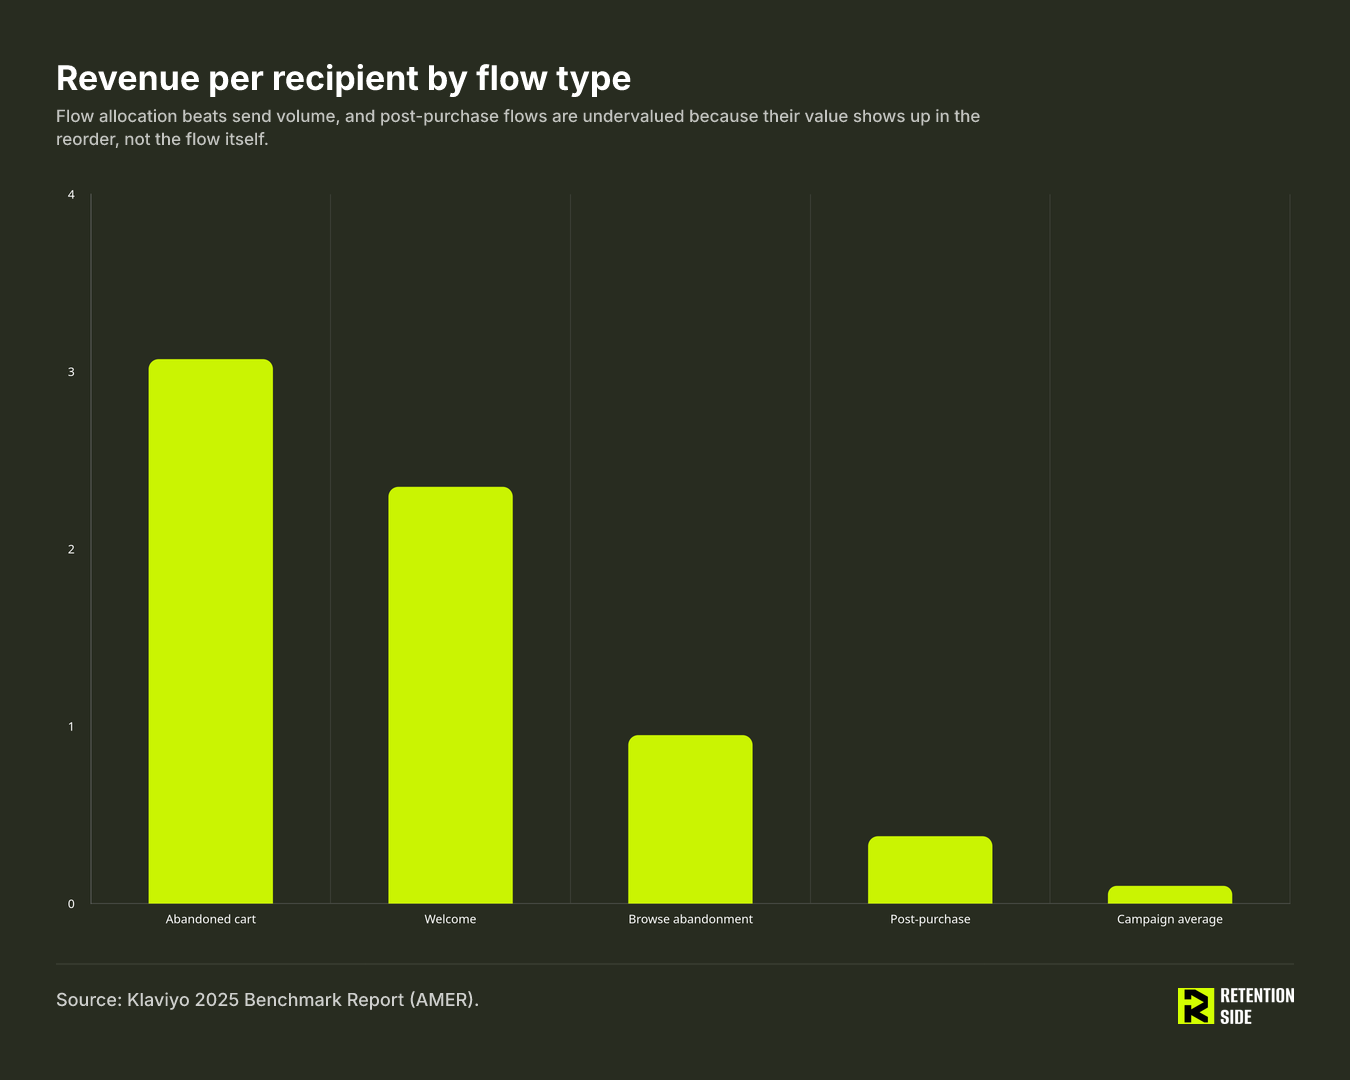
That combination, a high open rate paired with a low direct order rate, is exactly what you’d expect if post-purchase flows are doing their real job: setting usage expectations, not closing a sale. In a supplements or skincare brand, this is the window where customers decide whether the product is “working,” and that decision drives the order-two conversion far more than any discount email will. Treating post-purchase as an education window rather than an underperforming sales flow changes how you should write and time it. The revenue attribution shows up later, in the reorder, not in the flow’s own placed-order rate.
The wellness-specific traps that generic retention advice misses
A few patterns are specific enough to health and wellness that they don’t show up in cross-category retention playbooks.
Functional and ritual products skip more than staples. Recharge’s data shows functional or ritual products, probiotics, collagen, adaptogens, electrolytes, process only 69.5% of scheduled orders compared to 73.1% for commodity consumables, and get skipped roughly 75% more often, at a 6.9% skip rate versus 4.0%, according to Recharge’s wellness subscription research. If your product category sits closer to “ritual” than “staple,” expect a higher baseline skip rate and design your win-back and skip-recovery flows around it rather than treating every skip as a churn signal.
The perceived-efficacy problem is a real churn driver, and it’s timing-specific. Wellness products that don’t produce a fast, felt effect lose customers in the 60-90 day window when the customer quietly decides the product “isn’t working,” even if it’s working exactly as intended on a slower biological timeline. This is a wellness-specific version of buyer’s remorse, and it needs to be addressed with expectation-setting content well before that window closes, not with a discount after the customer has already mentally churned.
Price-driven brand-hopping is a structural risk, not a personality flaw. Klaviyo’s 2024 state of eCommerce data found that 78% of health and beauty consumers cite quality as their top purchase factor, with price close behind, while brand reputation (42%) and reviews (39%) trail well back, per Klaviyo’s health and beauty industry benchmarks. The same research notes that roughly half of brands offer loyalty programs despite majority consumer usage of them. When price sits this close to quality as a purchase driver, a subscriber who finds a cheaper equivalent on Amazon or in retail has very little brand-loyalty friction stopping them from switching. This is one of the reasons loyalty program structure matters more in this category than in categories where brand attachment runs deeper.
What to build for in 2026
Given where the curve breaks and what the category rewards, the practical priorities for a health and wellness brand this year come down to four things.
First, design the subscription experience around the first reorder specifically, not the general customer journey. That means dosage or usage reminders timed to your actual depletion cycle, proactive “your order is coming” touches that set expectations before renewal, and an easy skip-or-adjust option that reduces outright cancellation in favor of a pause. Recharge’s data on skip behavior in functional products makes clear that flexibility reduces churn more than rigid renewal dates do.
Second, treat post-purchase sequencing as an education-first opportunity, not a sales flow that’s underperforming because it doesn’t convert like abandoned cart. Its job is setting realistic expectations about when and how the customer will feel or see results, which directly reduces the perceived-efficacy churn that shows up 60-90 days in.
Third, calibrate win-back timing to your product’s actual depletion cycle rather than a generic 30-60-90 day sequence. A supplement designed to last 30 days needs a different win-back cadence than a skincare product meant to last 60. Sending a win-back campaign before the customer has plausibly run out of product wastes the message and can read as tone-deaf.
Fourth, build loyalty as infrastructure, not as a recurring discount mechanism. Given how closely price and quality compete as purchase drivers in this category, a loyalty program that only offers percentage-off rewards reinforces the exact price sensitivity that makes brand-hopping easy. Structuring loyalty around access, education, or product-specific perks gives customers a reason to stay that isn’t purely financial, which matters more here than in categories with stronger inherent brand attachment.
How to read your own numbers
None of the benchmarks above are useful if you apply them without matching your measurement window and cohort to the source. A 29% twelve-month repeat rate on an all-customer panel and a 45% rate on a revenue-qualified cohort of established brands are both “correct,” they’re just answering different questions. The number that should actually guide your decisions is your own depletion cycle: if your product runs out in 30 days, your retention program should be built around what happens in the days surrounding that 30-day mark, not around whatever cadence a generic playbook suggests.
Health and wellness brands running above $300,000 a month have real subscriber and order volume to build cohort-specific benchmarks from their own data instead of borrowing someone else’s median. That’s the shift worth making in 2026: from asking whether your repeat rate looks acceptable against a blended industry number, to asking whether your first-to-second-order conversion is where it should be given the specific product, cycle, and customer you’re serving. That’s the number that actually predicts long-term revenue from existing customers, and it’s the one most benchmark reports never isolate.